
For SBA-financed acquisitions, C corporations generally offer stronger asset protection for personal assets than LLCs due to the statutory corporate veil, while LLCs provide superior flexibility for pass-through taxation and operational control. C corps suit buyers seeking maximum liability insulation and institutional credibility, whereas LLCs fit operators prioritizing tax efficiency and simpler governance. Warren Kalyan advises clients on these structural choices to align legal protection with financing requirements.
Understanding the Corporate Veil in C Corporations
A C corporation is a separate legal entity that shields shareholders from personal liability for corporate debts and obligations. This separation, known as the corporate veil, is the primary mechanism for asset protection. In SBA-financed deals, the SBA often requires personal guarantees from the buyer, which can pierce this veil. However, the C corp structure still isolates the acquired business assets from the buyer's other personal holdings. This isolation is critical when the acquired entity faces litigation or creditor claims post-closing.
Statutory Protections and Creditor Claims
C corporations benefit from well-established case law regarding the corporate veil. Courts are generally reluctant to pierce the veil of a properly maintained C corporation. This stability provides a predictable layer of protection for the buyer's personal assets. When an SBA loan is secured by business assets, the C corp structure ensures that only those specific assets are at risk, not the buyer's home or personal savings, unless a personal guarantee is triggered.
LLC Liability Shield and Operational Flexibility
An LLC is a hybrid entity that combines the liability protection of a corporation with the tax flexibility of a partnership. LLCs offer a strong liability shield, but the legal landscape is less settled than for C corporations. In many jurisdictions, LLCs provide 'charging order' protection, which limits a creditor's ability to seize the LLC itself. Instead, the creditor can only claim the member's share of profits. This is a crucial distinction for asset protection in SBA acquisitions where the buyer holds a membership interest.
Single-Member LLCs and Veil Piercing
Single-member LLCs face a higher risk of veil piercing compared to multi-member LLCs or C corporations. Courts may treat a single-member LLC as an alter ego of the owner if formalities are not observed. For SBA buyers, this means maintaining strict separation between personal and business finances is essential. Failure to do so can expose personal assets to business creditors, undermining the primary goal of asset protection.
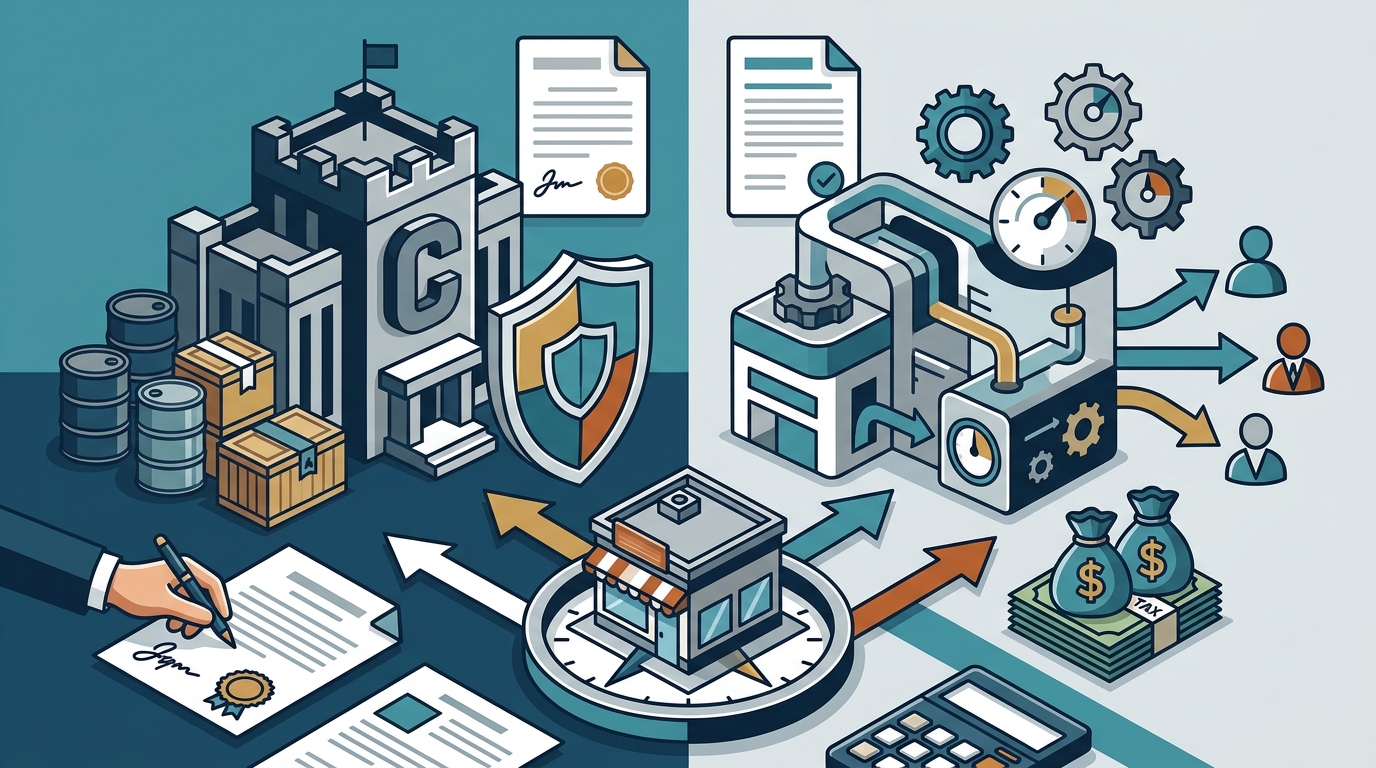
Comparison of Asset Protection Features
| Criteria | C Corporation | LLC |
|---|---|---|
| Liability Shield Strength | Strong, well-established case law | Strong, but varies by state and member count |
| Charging Order Protection | Not applicable (shareholders hold shares) | Yes, limits creditor access to entity |
| Veil Piercing Risk | Low if formalities maintained | Moderate, higher for single-member LLCs |
| SBA Personal Guarantee Impact | Guarantee pierces veil for guaranteed debts | Guarantee pierces veil for guaranteed debts |
| Tax Treatment | Double taxation (corporate and shareholder) | Pass-through taxation (single layer) |
| Operational Formalities | High (board meetings, minutes, officers) | Low (operating agreement, annual reports) |
Choosing the Right Entity for Your Acquisition
Selecting the correct entity type is a strategic decision that impacts both liability and tax outcomes. The choice should align with the buyer's long-term goals and the specific risks of the acquired business.
Choose a C Corporation If
Choose a C corporation if you are acquiring a business with high litigation risk or significant debt. The robust corporate veil provides the strongest defense against creditor claims. C corps are also preferred by institutional investors and may be required for certain SBA loan structures. If you plan to raise outside capital or go public in the future, a C corp is the standard structure.
Choose an LLC If
Impact of SBA Financing on Entity Choice
SBA loans often come with personal guarantees, which significantly impact asset protection. The guarantee means that if the business defaults, the SBA can pursue the buyer's personal assets. This applies to both C corps and LLCs. However, the entity structure still determines how other creditors can access business assets. A C corp may limit other creditors to the corporate assets, while an LLC may expose the member's interest to charging orders.
Structuring the Acquisition Entity
Many buyers use a holding company structure to enhance asset protection. For example, a C corp holding company can own the LLC that operates the business. This adds an extra layer of separation between the operating assets and the buyer's personal assets. Warren Kalyan advises clients on these multi-tier structures to maximize protection while complying with SBA requirements.
Frequently Asked Questions
Does an SBA personal guarantee negate the liability protection of a C corp or LLC?
Yes, a personal guarantee allows the SBA to pursue personal assets for the guaranteed debt. However, the entity structure still protects personal assets from other business creditors and litigation claims not covered by the guarantee.
Can I convert an LLC to a C corporation after an SBA acquisition?
Yes, but the conversion may have tax implications and could trigger SBA consent requirements. It is essential to consult with legal and tax advisors before converting to ensure compliance with the loan agreement.
Which entity type is better for protecting personal assets from business lawsuits?
C corporations generally offer stronger protection against business lawsuits due to the well-established corporate veil. LLCs provide good protection, but single-member LLCs face a higher risk of veil piercing if formalities are not maintained.
How does the SBA view LLCs versus C corps in loan applications?
The SBA accepts both entity types for financing. However, some SBA lenders may prefer C corporations for larger deals due to their stability and governance structure. The choice should be based on your specific business needs and tax strategy.
What are the switching costs if I choose the wrong entity type?
Switching entity types can involve significant tax costs, legal fees, and administrative work. It may also require SBA consent and could affect the loan terms. Choosing the right entity upfront is critical to avoid these costs.
Conclusion
Asset protection in SBA-financed acquisitions requires a careful balance between liability shielding and tax efficiency. C corporations offer the strongest legal protection, while LLCs provide tax flexibility and operational simplicity. The right choice depends on your specific risk profile and long-term goals. Warren Kalyan provides expert guidance on entity selection and structuring to ensure your acquisition is protected and compliant. To discuss your acquisition strategy, .