
How LLC Structure Protects Personal Assets in SBA Business Acquisitions
Forming a single-member LLC to acquire a business with SBA financing creates a legal barrier between your personal wealth and the company's operational debts. This structure limits creditor access to your home, savings, and other personal assets, provided you maintain strict corporate formalities and avoid personal guarantees that pierce the liability shield. For additional details, review the Contact Us warren kalyan.
The Legal Barrier of Entity Formation
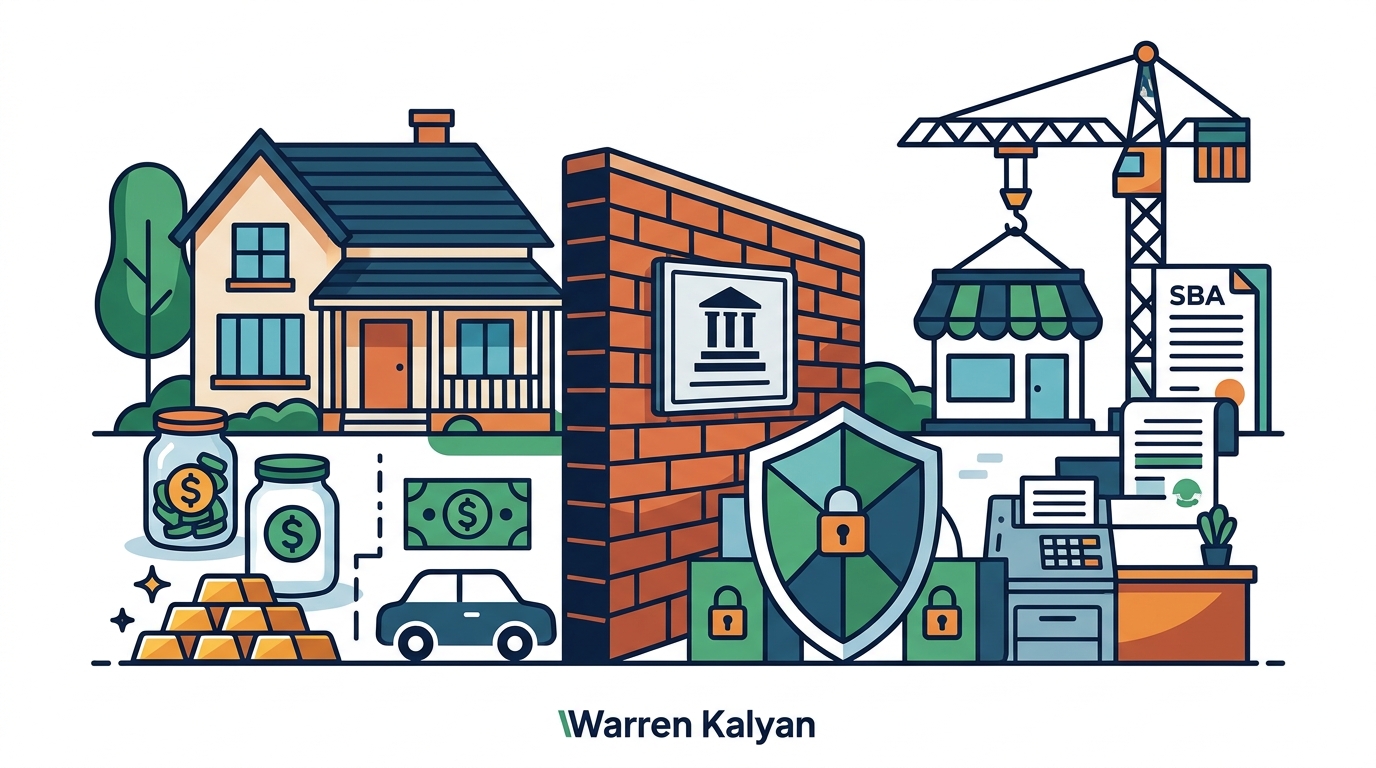
Choosing the right entity is the first step in isolating personal risk. A Limited Liability Company (LLC) is a business structure that provides its owners with limited liability protection, meaning creditors generally cannot pursue the owner's personal assets to satisfy business debts. When you buy a business, you are not just purchasing assets; you are assuming the operational risks of running that enterprise. By acquiring the target through a newly formed LLC, you ensure that any future lawsuits, contract breaches, or operational failures remain contained within the corporate entity. For additional details, review the Texas and New York.
This separation is critical for small business owners who often have significant personal net worth. If the acquired business faces a major liability event, such as a slip-and-fall injury or a supply chain contract dispute, the claim is directed at the LLC. The LLC's assets, which include the purchased business, are at risk, but your personal bank accounts and real estate remain protected under state law. This structural choice is a foundational element of corporate planning and structuring, ensuring that your personal financial stability is not tethered to the business's performance.
SBA Financing and Personal Liability
While the personal guarantee exposes your personal assets to the SBA if you default on the loan, it does not expose them to the business's other creditors. This distinction is vital. If the business fails to pay a vendor or faces a lawsuit from a customer, your personal assets are protected by the LLC structure. The personal guarantee only triggers if you fail to repay the SBA loan itself. Therefore, the LLC still serves as a shield against the vast majority of operational liabilities, even when SBA financing is involved. Understanding this nuance is essential for managing risk effectively during the acquisition process.
Maintaining Operational Formalities
The liability protection offered by an LLC is not automatic; it requires consistent maintenance. Courts can pierce the corporate veil if they determine that the LLC is merely an alter ego of its owner. This happens when the owner commingles personal and business funds, fails to keep separate records, or treats the LLC as a personal checking account. To maintain the legal barrier, you must operate the LLC with discipline and professionalism.
Specific actions include opening separate business bank accounts, maintaining accurate financial records, and holding regular meetings even for single-member LLCs. These formalities demonstrate to courts and creditors that the LLC is a distinct legal entity. Failure to adhere to these standards can result in the loss of liability protection, leaving your personal assets vulnerable to business debts. Proper corporate governance is not just a bureaucratic exercise; it is a critical component of asset protection strategy.
Strategic Asset Protection
Building a robust asset protection strategy involves more than just forming an LLC. It requires a comprehensive approach to managing risk and structuring ownership. One effective method is to hold the LLC membership interest in a separate trust or another entity. This adds an additional layer of protection, making it more difficult for creditors to reach the underlying business assets. Additionally, maintaining adequate insurance coverage, such as general liability and professional liability policies, provides a financial buffer against potential claims.
Consulting with legal and financial professionals is crucial for tailoring this strategy to your specific situation. Each acquisition is unique, and the optimal structure depends on factors such as the type of business, the financing terms, and your personal financial goals. By working with experts, you can ensure that your asset protection plan is comprehensive and effective. This proactive approach helps you focus on growing the business while safeguarding your personal wealth.
Key Takeaways
- Forming an LLC creates a legal barrier that protects personal assets from business debts.
- SBA financing requires a personal guarantee, but this only exposes assets to the SBA, not other creditors.
- Maintaining strict corporate formalities is essential to prevent the corporate veil from being pierced.
- Separate bank accounts and accurate record-keeping are critical for preserving liability protection.
- Additional layers of protection, such as trusts and insurance, can enhance your asset protection strategy.
- Consulting with legal professionals ensures your structure is tailored to your specific acquisition and risk profile.
Frequently Asked Questions
Does an LLC protect my personal assets from SBA loans?
An LLC protects your personal assets from general business debts, but SBA loans typically require a personal guarantee. This means your personal assets are at risk if you default on the SBA loan, but they remain protected from other business liabilities.
What happens if I commingle personal and business funds?
Commingling funds can lead to the piercing of the corporate veil, where courts may hold you personally liable for business debts. To maintain protection, you must keep personal and business finances strictly separate.
Is a single-member LLC sufficient for asset protection?
Do I need a lawyer to form an LLC for an acquisition?
While you can form an LLC yourself, working with a lawyer ensures that the structure is optimized for your specific acquisition and that all legal requirements are met to maintain liability protection.
How does SBA financing affect my personal credit?
Because SBA loans require a personal guarantee, your personal credit is directly tied to the loan's performance. Defaulting on the loan can negatively impact your personal credit score and expose your assets to collection efforts.
Can I use an LLC to protect assets from a lawsuit?
Yes, an LLC can protect your personal assets from lawsuits related to business operations. However, it does not protect assets from personal liabilities, such as a car accident or a personal loan default.